TOP
英國出版界指標大獎肯定!A.F. Steadman 獲年度作家,《史坎德》系列帶你踏上熱血奇幻旅程
搜尋結果 /

Crc Financial Mathematics

共 71 筆
第1 / 2 頁
出版日:2016/09/16 作者:Tze Leung Lai; Haipeng Xing  出版社:CRC Press UK  裝訂:精裝
Following the recent financial crisis, risk management in financial institutions, particularly in banks, has attracted widespread attention and discussion. Novel modeling approaches and courses to edu
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2014/02/25 作者:Giuseppe Campolieti; Roman Makarov  出版社:Taylor & Francis  裝訂:精裝
This text offers a comprehensive, self-contained, and unified treatment of the theory and application of mathematical methods behind modern-day financial mathematics. It introduces the financial theor
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2013/12/20 作者:Nicolas Privault  出版社:Taylor & Francis  裝訂:精裝
"Preface This text is an introduction to pricing and hedging in discrete and continuous time financial models without friction (i.e. without transaction costs), with an emphasis on the complementarity
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2013/12/15 作者:Guyon; julien; Pierre-henry Labordere  出版社:Taylor & Francis  裝訂:精裝
Collecting many methods that have previously been scattered in the literature, this book presents advanced techniques for solving high-dimensional nonlinear problems. Designed for practitioners, it is
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2013/07/31 作者:Thierry Roncalli  出版社:Taylor & Francis  裝訂:精裝
Although portfolio management didn’t change much during the 40 years after the seminal works of Markowitz and Sharpe, the development of risk budgeting techniques marked an important milestone in the
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2013/04/30 作者:Masaaki Kijima  出版社:Taylor & Francis  裝訂:精裝
Financial engineering has been proven to be a useful tool for risk management, but using the theory in practice requires a thorough understanding of the risks and ethical standards involved. Stochasti
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2012/03/26 作者:Erik Schlogl  出版社:Chapman & Hall  裝訂:精裝
A textbook for studentsand a reference guide for professionals, this text builds a foundation in the key methods and models of quantitative finance from the perspective of their implementation i
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2012/03/15 作者:Hui Wang  出版社:Chapman & Hall  裝訂:精裝
Developed from the author’s course on Monte Carlo simulation at Brown University, Monte Carlo Simulation with Applications to Finance provides a self-contained introduction to Monte Carlo method
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2012/02/03 作者:Peter Buchen  出版社:CRC PRESS  裝訂:精裝
Fully derives every price formula for the exotic optionsDevelops special pricing techniques based on the no-arbitrage principleContains a significant amount of original, previously unpublished materia
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
Option Valuation ─ A First Course in Financial Mathematics
90 折
出版日:2011/12/01 作者:Hugo D. Junghenn  出版社:CRC PRESS  裝訂:精裝
Offers a straightforward account of the principles and models of option pricingFocuses on the (discrete time) binomial model and the (continuous time) Black-Scholes-Merton modelDevelops probability th
優惠價: 9 2281
無庫存
出版日:2011/05/26 作者:Ali Hirsa  出版社:CRC Press UK  裝訂:精裝
As today’s financial products have become more complex, quantitative analysts, financial engineers, and others in the financial industry now require robust techniques for numerical analysis. Covering
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2005/12/15 作者:Jerome Detemple  出版社:Chapman & Hall  裝訂:精裝
While the valuation of standard American option contracts has now achieved a fair degree of maturity, much work remains to be done regarding the new contractual forms that are constantly emerging in r
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
Financial Mathematics:A Comprehensive Treatment in Discrete Time
90 折
The book has been tested and refined through years of classroom teaching experience. With an abundance of examples, problems, and fully worked out solutions, the text introduces the financial theory and relevant mathematical methods in a mathematically rigorous yet engaging way.This textbook provides complete coverage of discrete-time financial models that form the cornerstones of financial derivative pricing theory. Unlike similar texts in the field, this one presents multiple problem-solving approaches, linking related comprehensive techniques for pricing different types of financial derivatives.Key features: In-depth coverage of discrete-time theory and methodology. Numerous, fully worked out examples and exercises in every chapter. Mathematically rigorous and consistent yet bridging various basic and more advanced concepts. Judicious balance of financial theory, mathematical, and computational methods. Guide to Material. This revision contains: Almost 200 pages worth of new materia

優惠價: 9 3239
無庫存
出版日:2022/05/20 作者:Chris Kelliher (Fidelity Investments. USA)  出版社:PBKTYFRL  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2022/05/09 作者:Yue Kuen Kwok; Wendong Zheng  出版社:PBKTYFRL  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2021/07/14 作者:ALOS  出版社:Chapman & Hall  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2021/06/30 作者:Vsevolod K. Malinovskii  出版社:PBKTYFRL  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2021/01/01 作者:Liang (Georgia State University Peng Atlanta USA); Zhengjun Zhang  出版社:Taylor & Francis Inc  裝訂:精裝

若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2020/09/01 作者:Guillaume Coqueret and Tony Guida  出版社:Chapman & Hall  裝訂:精裝
The aim of the book is to give an interpretation of ML tools through the lens of factor investing. Concepts illustrated with examples on the same (public) dataset throughout the book. Provides code sa
無法訂購
出版日:2020/09/01 作者:Guillaume Coqueret and Tony Guida  出版社:Chapman & Hall  裝訂:平裝
The aim of the book is to give an interpretation of ML tools through the lens of factor investing. Concepts illustrated with examples on the same (public) dataset throughout the book. Provides code sa
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2020/06/12 作者:Mohamed Abdelghani; Alexander Melnikov  出版社:PBKTYFRL  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2020/05/15 出版社:PBKTYFRL  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2020/03/16 作者:Daniele Ritelli; Giulia Spaletta  出版社:Taylor & Francis Inc  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
Financial Modelling in Commodity Markets
90 折
出版日:2019/12/09 作者:Viviana Fanelli  出版社:PBKTYFRL  裝訂:平裝
優惠價: 9 2807
無庫存
出版日:2019/12/09 作者:Viviana Fanelli  出版社:PBKTYFRL  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2019/07/11 作者:Guojun Gan; Emiliano A. Valdez  出版社:Chapman & Hall  裝訂:精裝
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2019/03/25 作者:Hugo D. Junghenn  出版社:Chapman & Hall  裝訂:精裝
Introduction to Financial Mathematics: Option Valuation, Second Edition is a well-rounded primer to the mathematics and models used in the valuation of financial derivatives. The book consists of ?fte
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2019/02/25 作者:Lixin Wu  出版社:CRC Pr I Llc  裝訂:精裝
Containing many results that are new, or which exist only in recent research articles, Interest Rate Modeling: Theory and Practice, 2nd Edition portrays the theory of interest rate modeling as a three
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2018/11/06 作者:Edward E. Qian  出版社:Chapman & Hall  裝訂:精裝
The goal of this book is to provide mathematical and empirical analysis of the effects of portfolio rebalancing on portfolio returns and risks. The mathematical analysis answers the question of when a
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2018/06/13 作者:Ambrose Lo  出版社:Chapman & Hall  裝訂:精裝
The proliferation of financial derivatives over the past decades, options in particular, has underscored the increasing importance of derivative pricing literacy among students, researchers, and pract
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2017/09/11 作者:Alexander Melnikov; Amir Nosrati  出版社:Chapman & Hall  裝訂:精裝
This book focuses on the application of the partial hedging approach from modern math finance to equity-linked life insurance contracts. It provides an accessible, up-to-date introduction to quantifyi
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2017/07/12 作者:Pierre Henry-labordere  出版社:Chapman & Hall  裝訂:精裝
This book focuses on the computation of model-independent bounds for exotic options consistent with market prices of liquid instruments such as Vanilla options. The author gives an overview of Marting
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2016/10/25 作者:John Armstrong  出版社:Productivity Press  裝訂:精裝
This book simultaneously introduces C++ programming techniques and numerical techniques for derivative pricing and risk management. The techniques covered include Monte Carlo pricing, finite differenc
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2016/10/06 作者:Peter Tankov; Rama Cont  出版社:CRC Press UK  裝訂:精裝
Including a new chapter on credit risk modelling and new developments in econometrics, the new edition of this bestselling resource provides an accessible overview of financials models based on jump p
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2016/02/03 作者:Jeannine R. Studer; Theresa A. Quigney  出版社:Apple Academic Press UK  裝訂:精裝
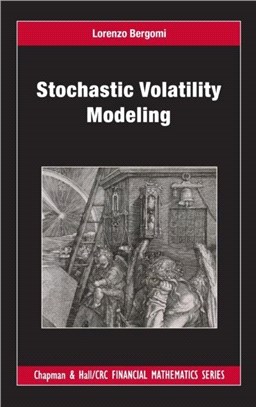
In this book, author Lorenzo Bergomipresents readers with an examination of the methods used to employ stochastic volatility to address a variety of issues that come from the modeling of derivatives.
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2015/05/15 作者:M. A. H. Dempster (EDT); Ke Tang (EDT)  出版社:Productivity Press  裝訂:精裝
This book covers the fundamental theory of and derivatives pricing for major commodity markets as well as the interaction between commodity prices and the real economy and other financial markets. Aft
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2010/01/19 作者:Douglas Kennedy  出版社:Chapman & Hall  裝訂:精裝
Filling the void between surveys of the field with relatively light mathematical content and books with a rigorous, formal approach to stochastic integration and probabilistic ideas, Stochastic Financ
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2007/05/07 作者:Edward E. Qian; Ronald H. Hua; Eric H. Sorensen  出版社:Chapman & Hall  裝訂:精裝
Quantitative equity portfolio management combines theories and advanced techniques from several disciplines, including financial economics, accounting, mathematics, and operational research. While man
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
出版日:2006/10/26 作者:Christian Bluhm; Ludger Overbeck  出版社:Taylor & Francis  裝訂:精裝
This volume covers the topic of mathematical approaches for modeling structured products that are credit-linked to an underlying portfolio of credit-risky instruments. The authors do not present all t
若需訂購本書,請電洽客服 02-25006600[分機130、131]。
  • 共 71筆
    第 2 頁
  • 1
  • 2

暢銷榜

客服中心

收藏

會員專區